
Your kid spots a toy at the checkout and asks for it. You say no. Then comes the question that stops most parents cold: “Why not? Just get it.”
Here’s what makes those moments matter more than you might think. Research from Cambridge University found that most children’s money habits are formed by age 7. That means the patterns around saving, spending, and waiting start developing long before your child can count change, and they’re learning from watching you whether you plan the lessons or not.
The good news is you don’t need to be a finance whiz to raise a money-smart kid. Small, age-appropriate conversations work better than one big talk.
In this guide, you’ll find lessons broken down by age (starting with toddlers and running through the teen years), how to handle allowance and chores without the battles, simple ways to teach saving and spending, and the common mistakes parents make that quietly undo all that effort.
Let’s start with what your child can actually understand at each age, because that’s where the foundation gets built.
Why Teaching Kids About Money At A Young Age Pays Off For Life
Money habits don’t wait for adulthood to form. The patterns your child builds now, around saving, spending, and patience, tend to stick. That’s exactly why the early years matter so much, and why researchers keep coming back to one surprising age: seven.
How Kids Actually Learn About Money (Hint: They Watch You)
Long before your child can count coins, they’re studying you. Every card swipe at the grocery store, every sigh over a bill, every “we can’t afford that right now” gets filed away. This is called observational learning, and it’s how most kids absorb their first money attitudes.
The Cambridge University study often cited on this topic found that children grasp money concepts like saving, delay, and value by their seventh birthday. By then, they’ve already built a mental model of how money works in your house.
The tricky part is that kids pick things up from conversations you don’t even realize they hear. A tense exchange about an unexpected expense teaches them money equals stress, even if you never say it outright.
The fix isn’t perfection. It’s narrating your choices out loud. Say things like “I’m comparing prices so we can save for our trip” or “I’m putting this back because we budgeted for groceries, not toys.” Those small comments turn routine errands into lessons, no formal setup required.
The Real Cost of Skipping Money Lessons Early
When kids reach adulthood without any financial education, they learn through expensive trial and error. Credit cards feel like free money until interest piles up. Student loans get signed without a real sense of what repayment looks like. Many young adults lean on parents for years simply because nobody showed them the basics.
Here’s the encouraging flip side: research on early financial habits, including the Cambridge findings, links early money understanding to better saving behavior, less debt, and more financial confidence later in life. Adults who grasped money concepts young tend to handle budgeting and credit decisions with less anxiety.
The lessons don’t need to be complicated, either. Talking through simple choices now (spend or save, needs or wants) builds judgment that compounds over decades. A little effort at five or six can spare your child a lot of stress at twenty-five.
Money Lessons By Age: What To Teach From Toddler To Teen
Kids can handle more money concepts than most parents give them credit for. The trick is matching the lesson to the stage. A three-year-old doesn’t need to hear about interest rates, and a sixteen-year-old will roll their eyes at a piggy bank. Here’s what works at each age, with activities you can start this week.
Ages 3 to 7: Coins, Counting, and the Idea That Things Cost Money
At this stage, money is a physical thing to your child. Coins have colors and sizes, and everything else is invisible. So start with the tangible.
Help them identify coins by name and value, then turn it into a sorting game. A pile of mixed change and a few muffin tins can occupy a five-year-old longer than you’d expect, and they’re learning currency basics while they play.
Next, connect money to the world they see. At checkout, hand your child the cash and let them pay the cashier. Say plainly, “We give money to the store, and then the bananas are ours.” That one sentence explains more than an hour of lecturing.
A cash jar is the single best tool for this age. Use a clear jar (or a clear plastic container) so they can actually watch the pile grow. When they want a small toy, count the money out together and talk about how close they are. Waiting becomes concrete instead of abstract.
Playing store is another winner. Set up a shop with priced stuffed animals, give them a few coins, and let them buy and “sell.” They’ll grasp the exchange idea fast, and honestly, it’s fun for you too.
The goal here is simple: money is real, money buys things, and money can run out. That’s plenty for a seven-year-old.
Ages 8 to 12: Allowance, Saving Goals, and Smart Spending Choices
Elementary and middle school kids are ready for money they manage themselves. This is the age to introduce an allowance or commission, money tied to chores done rather than given automatically. Many parents prefer commission because it links work and income, a lesson that ages well.
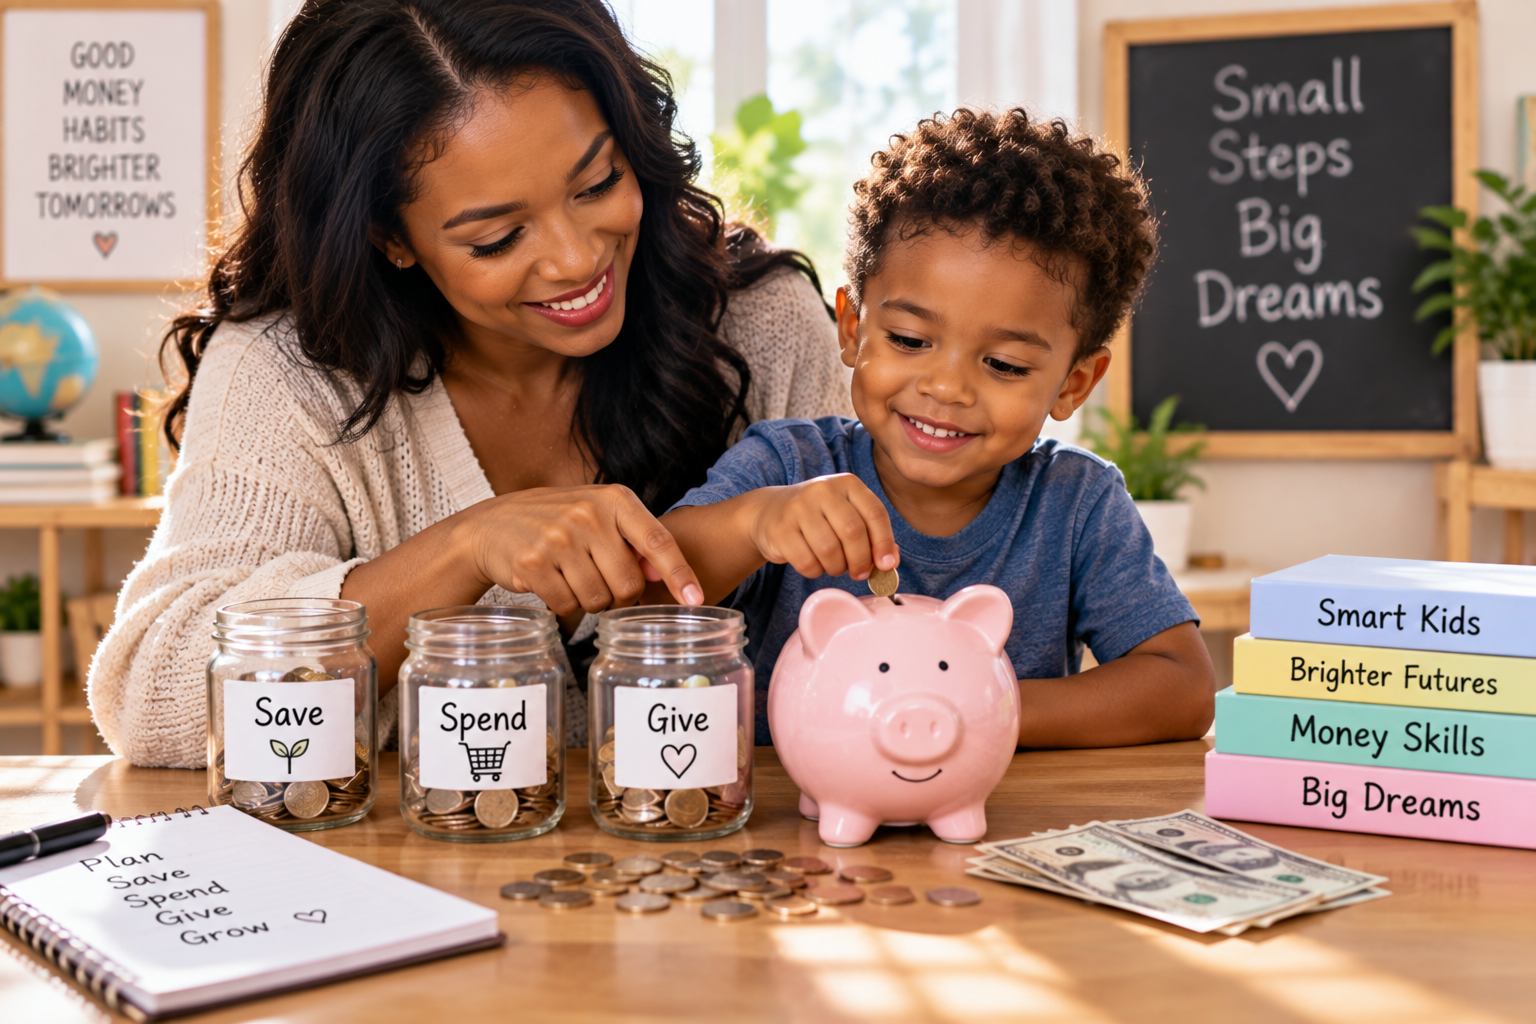
Then set up the classic three-jar system: save, spend, and give. Every dollar gets split among the three jars. A common split is 50/40/10, but the exact numbers matter less than the habit of dividing money on purpose before spending it.
This is also the perfect window for a real savings goal. A bike, a video game, a pair of shoes they’ve been begging for. Write the target price on a piece of paper taped to the jar. Each week, your child sees the gap shrink, and that feeling of progress is what builds a saver.
Bring them into price comparisons at the store, too. Same crackers, two brands, different prices. Ask which they’d pick and why. You’re teaching them that choices exist and that spending is a decision, not a reflex.
Digital tools can help here as well. Kid-friendly debit apps like Greenlight or GoHenry let tweens practice with a card under your supervision, with parental controls and spending visibility built in. Just make sure the physical jars come first, since kids this age still benefit from seeing money as a limited object before it becomes a number on a screen.
Ages 13 to 18: Bank Accounts, Budgeting, and First Jobs
Teenagers can handle adult concepts, so give them adult tools. Start by opening a teen checking account with a debit card, most banks and credit unions offer youth accounts with low or no fees. Managing a real account teaches more in three months than any worksheet ever will.
With an account in place, help them build a simple budget. Income on one side, planned spending on the other. A notes app works fine. The format doesn’t matter; the act of deciding where money goes before it disappears does.
Two concepts deserve real conversation time before they leave your house:
- Compound interest, because it either works for them (savings and investing) or against them (credit card debt). Show them a calculator and let a $1,000 balance grow at 20% interest. The number does the convincing.
- Credit scores, since a thin or damaged credit file makes renting an apartment or financing a car expensive later.
Encourage a first job or side hustle, whether that’s babysitting, mowing lawns, or working retail. Then use that first paycheck for the tax lesson: show them the difference between gross pay and take-home pay. Most teens are genuinely shocked by the gap, and that surprise is a useful thing to have at fifteen instead of twenty-five.
By graduation, your teen should know how to deposit a check, stick to a budget for a month, and explain why carrying a credit card balance is expensive. Those three skills put them ahead of most young adults.
Allowance, Chores, and Earning: Should Kids Work For Their Money?
Two main camps exist on kids and money. One hands over a set allowance with no strings attached. The other ties every dollar to chores done. Both can work, and honest parents land somewhere in the middle more often than they admit.
The case for a plain allowance is that money lessons need practice. If income only arrives when chores get done, a child who skips chores also skips the learning. The downside is obvious too: money shows up regardless of effort, which muddies the connection between work and pay.
Why Many Experts Recommend Paying For Chores Instead
The commission model treats your house like a tiny economy. Do the job, get paid. Skip it, and payday shrinks. That setup mirrors adult life better than an automatic allowance ever could, and kids grasp it fast because the feedback is instant.
Start by splitting chores into two categories. Some work is simply part of being in the family:
- Making their bed
- Clearing their own dishes
- Putting dirty clothes in the hamper
Then set a small paid list on top, matched to age. A six-year-old might earn a dollar for watering plants. A ten-year-old can wash the car or vacuum for a few dollars. Keep the paid tasks optional so the lesson stays clean: extra effort creates extra income.
Teaching Kids To Save For What They Really Want
Earning is half the equation; keeping money is the other half. Delayed gratification is the skill underneath it all, and the famous marshmallow test found that kids who could wait for a bigger reward tended to do better in life across many measures.
Make waiting concrete with a savings goal. Write the price of the wanted item on the jar and let your child watch the gap close week by week. You can also add matching contributions, the way employers match 401(k) deposits, so every saved dollar becomes a dollar fifty. It rewards patience instead of punishing it.
Then celebrate when the goal is hit. Mark the purchase, talk about how it felt to wait, and start the next goal while the momentum is fresh.
Everyday Ways To Talk About Money Without Making It Awkward
You don’t need a lesson plan or a laminated worksheet to teach your kids about money. The best lessons hide inside errands you’re already running. A Tuesday grocery run can cover more financial ground than a formal sit-down talk, mostly because your child is relaxed, present, and holding the snacks. The trick is deciding ahead of time which moment you’ll turn into a mini lesson, then letting the rest of the trip stay normal.
Turning Grocery Runs and Errands Into Money Lessons
Start with the list. Hand your child a copy (pictures work for pre-readers) and make them the keeper of it. Sticking to a list teaches that spending is planned, not impulsive.
In the cereal aisle, compare unit prices out loud. Say, “This box costs more, but look, it’s bigger. Which one gives us more for our money?” Even a six-year-old can pick the better deal once you frame it as a puzzle.
Coupons are another easy win. Let your child hold them and match each one to the right item on the shelf. When the total drops at checkout, point at it. “That coupon just saved us a dollar. That’s a dollar we keep.”
Finally, hand over the cash. Letting your child pay the cashier and count the change back turns an abstract idea into something they can feel. The exchange happens right in front of them, and it sticks.
Talking About Wants Vs. Needs At The Store
The wants-versus-needs conversation works best when it stays calm and judgment-free. Instead of saying “we don’t need that, put it back,” try “that’s a want, and wants go on the birthday list.” You’re sorting items into categories, not shaming your child for wanting things. Everyone has wants; that’s normal.
Then give them the power to choose. Offer a small budget: “You have $3 for a treat today. The fruit snacks are $2 and the toy is $4.” Whatever they pick, honor it.
And here’s the part that’s hard for most parents: let them make the wrong call sometimes. If they blow their money on a cheap toy that breaks in a day, resist the “I told you so.” Ask one gentle question, “How do you feel about that toy now?” A $4 mistake at seven prevents a $400 mistake at seventeen.
The stakes are low now, which is exactly why these small errors are worth so much.
Helpful Tools And Apps For Teaching Kids About Money
You don’t have to build every lesson from scratch. A few well-chosen tools make the habits stick faster, because kids get to practice with something real. The right pick depends mostly on age, and here’s what works at each stage.
Physical Tools For Ages 3 To 8
Young kids learn through their hands, so tangible tools win here. A simple piggy bank or clear cash jar costs a few dollars (or nothing, if you reuse a mason jar) and lets a four-year-old watch savings physically grow. The three-jar system, one each for save, spend, and give, works well from about age five, and you can buy pre-labeled sets or make your own with tape and markers. Keep it visible and on their level; a jar buried in a closet teaches nothing.
Debit Card Apps For Ages 6 To 17
Once your child is ready for digital money, subscription apps handle the heavy lifting. Greenlight (around $5.99/month for the family) offers a debit card, parental controls, and savings goals, with an investing tier at a higher price point. GoHenry (about $4.99 per child monthly) has a strong app experience and chore-tracking built in. FamZoo (roughly $5.99/month per family) leans into prepaid cards and a family “bank” model where parents can charge interest or split allowances automatically.
All three let you see every transaction, so mistakes happen in a safe environment. For most families, one subscription covers every kid in the house.
Custodial Savings Accounts
For longer-term saving, open a custodial savings account at your bank or credit union. You control it until your child reaches adulthood, most pay modest interest, and fees are typically zero with a parent on the account. It pairs well with a debit app: the app handles everyday spending while the account holds bigger goals.
Start with the physical tools, then graduate to digital as your child shows they understand money as something limited. Layering works better than jumping straight to a card.
Common Mistakes Parents Make When Teaching Kids About Money
Even well-meaning parents undermine their own lessons. The four mistakes below come up in almost every household, and each one has a simple fix you can apply today.
Keeping Money Talk Completely Secret
Some parents grew up believing money is a private matter, so they never discuss budgets, bills, or salaries within earshot of their kids. The problem is that silence leaves children to guess, and kids who guess usually assume money is either infinite or shameful.
The fix is transparency at the right level. You don’t need to share your salary, but narrating everyday choices (“we’re skipping takeout this week because we’re saving for the trip”) shows your child that money decisions have reasons behind them.
Bailing Kids Out Of Every Mistake
It hurts to watch your child blow their savings on a toy that breaks in a day. Rescuing them anyway teaches the worst possible lesson: poor choices have no consequences, because someone always steps in.
Instead, let small losses sting a little. Ask how the purchase feels now, then help them plan differently next time. A $10 regret at eight years old is cheap tuition compared to a $10,000 credit card balance at twenty-eight.
Giving Large Handouts Instead Of Earning Opportunities
Handing over $20 whenever your child asks feels generous, but it severs the link between work and money. Kids who receive unearned cash often grow into adults who expect the same.
Tie money to effort instead. Paid chores, small side jobs, and commissions let your child connect income to labor, which is the habit that builds real financial independence later.
Complaining About Money In Front Of The Kids
Venting about bills in front of your children might feel harmless, but constant money stress becomes their money story. Kids who hear “we’re always broke” absorb anxiety, not financial literacy.
Save the venting for after bedtime, and share solutions out loud instead. Saying “we found $30 in our budget by cutting one subscription” models problem solving, and that framing sticks far better than worry ever will.
Conclusion
Raising money-smart kids doesn’t require a finance degree, a perfect budget, or even much extra time. It requires small, consistent conversations that start earlier than most parents think. The habits that shape your child’s financial future are forming right now, and you’re already the most important teacher they’ll ever have.
The good news is that everyday life hands you the curriculum for free. A trip to the grocery store, a clear jar of coins, a first savings goal: each one teaches something no worksheet can. What matters most is repetition, not expertise.
So pick one lesson from this guide and start this week. Sort coins with your toddler, set up a three-jar system with your eight-year-old, or sit down with your teen and open that first checking account. One small step today builds the confidence your child will carry for decades.
You don’t have to get it perfect. You just have to get it started. Your future adult will thank you for it.
Save pin for later
- Signs Your Baby Is Ready For Solid Foods - September 23, 2026
- First Trimester Survival Guide For Working Moms - September 23, 2026
- White Noise For Babies: Does It Really Help? - September 23, 2026